Quantitative Research & Algorithmic  Filters

High-fidelity market microstructure tracking, engineered for the opening 30 minutes of the regular trading session.


Your monthly contributions, funding continuous research, creating opportunity.

We Are Different

This is not a traditional retail stock alert service, chatroom, or financial advisory channel. Our private Discord server delivers raw, sub-500ms data streams straight from our proprietary, market-velocity filtering architecture.
Our philosophy is built on an elite, bulletproof foundation: transparent execution. Running an unedited live record in front of the world—win or lose—is the most powerful marketing mechanism in the entire trading industry.
The Opening Bell Firehose

At 9:30 AM, the US stock market forces retail daytraders to process thousands of chaotic symbols simultaneously. The resulting data overwhelm leads to decision paralysis, delayed execution, and chasing toxic momentum.

Proprietary Velocity Filtration

Our quantitative architecture monitors the live Alpaca market data pipeline, filtering out the noise to isolate a structural maximum of 15 high-velocity equity setups per session. We solve the single hardest problem in trading: knowing exactly where and when to look.

Engineered for Instant Execution

Our infrastructure strips away the layers of latency that cripple standard retail trading setups. We don't just find velocity; we deliver it before the market can price it in.
Sub-500ms API Architecture

Our system bypasses typical browser-based lag by compiling and executing filtration parameters directly at the server level. The resulting structural data outputs are pushed immediately into your private terminal loop with zero processing overhead.

Immutable Historical Archiving

Every single velocity trigger is instantly committed to our public, unedited field run logs. This open-source database gives subscribers the raw, permanent data sets required to backtest, audit, and verify system efficiency down to the exact millisecond.

Active Research Collaboration Access


      Premium Terminal Member
$49 / Month 
        ◦ Direct sub-500ms integration into our private Discord data feed.
        ◦ Real-time sequential TRIGGER VELOCITY and STRATEGY CLOSURE data
        ◦ Complete insulation from public stream visual latency delays.
        ◦ Full access to daily historical session logs and metric guides.

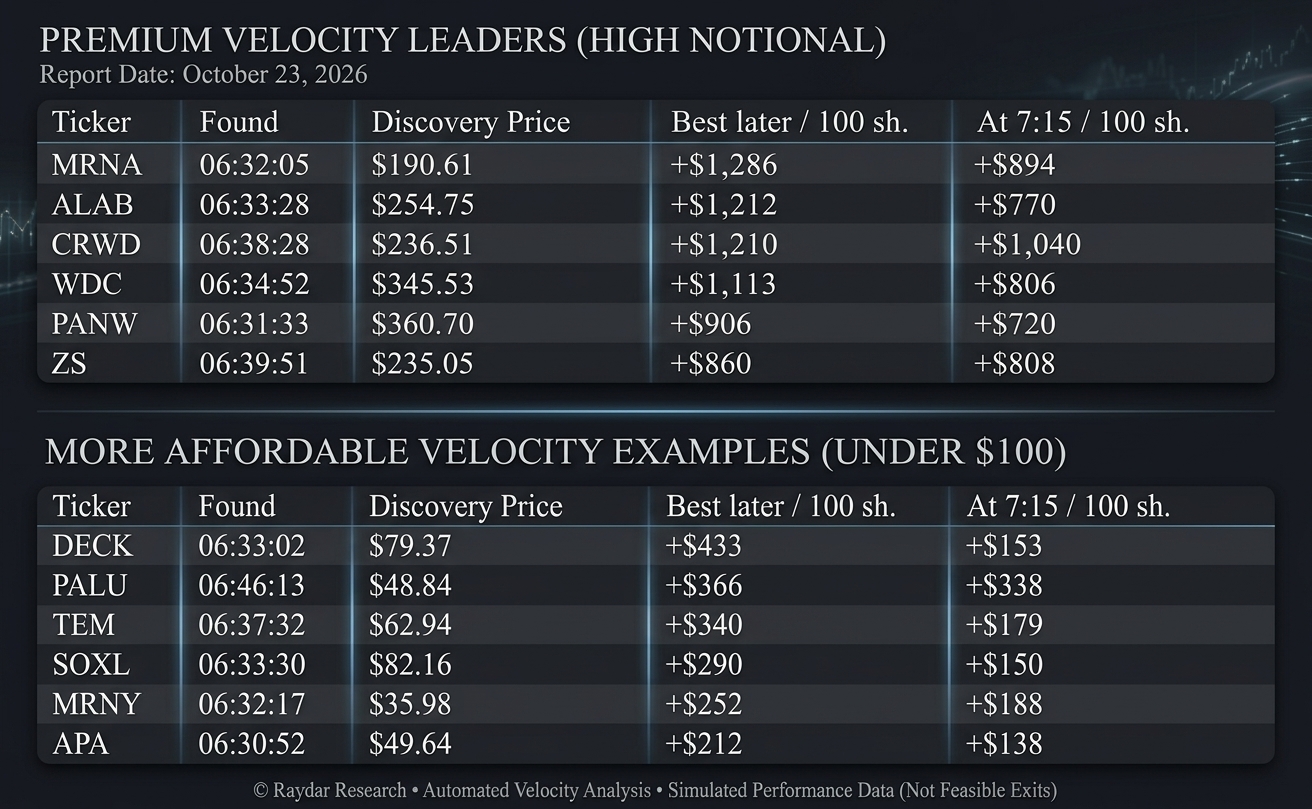
Observed Field Run Logs

At Raydar, institutional integrity isn’t just a concept—it’s engineered directly into our data pipeline. Our proprietary market-velocity filtering software strips away the noise of the opening bell to track elite momentum parameters in real time.
By delivering unedited, sub-500ms data outputs, we transform standard backtesting into a completely transparent, live-verification study. This immutable record archives the raw performance of our data engine—capturing every single velocity trigger exactly as it happens, win or lose.
We don't hide behind selective historical curation or cherry-picked wins. We publish the raw, sequential field run logs right in front of the world, providing researchers and subscribers with the concrete data necessary to observe real-time velocity metrics.

Quantitative Research Program Terms & Disclaimer

1. Nature of the Program
The Raydar.online platform operates strictly as an independent Quantitative Research & Experimental Software Development Program. All data, tickers, and sequential signals generated within this environment are the direct real-time output of proprietary algorithmic data models.
2. Informational and Educational Purpose Only
This program does not provide financial, investment, legal, or tax advice. No signal, trigger, or message constitutes a solicitation, recommendation, or endorsement to buy or sell any financial instrument. The system is designed to showcase the velocity filters and processing capabilities of proprietary experimental software.
3. Execution Characteristics & Dynamic Risk Realities
Subscribers acknowledge that the data feed operates in a high-velocity market microstructure environment (specifically during the opening 30 minutes of the regular trading session).
    • Selectivity: The data model is highly selective, filtering for extreme conditions. It may output zero signals on any given day, up to a structural maximum of 15 tickers per session.
    • Flash Aborts / Immediate Cancels/ Sell: The algorithm is designed to protect mock capital pools by terminating or canceling trade ideas within seconds if immediate velocity parameters break down. Subscribers acknowledge that immediate sequential cancels or rapid exit signals are a core design characteristic of the experimental logic, intended to absorb negligible, minimal friction rather than chasing decaying momentum.
4. Simulation and Performance Realities
Any live streaming visuals (including YouTube broadcasts via OBS) or performance logs are based on real-time market data processed through simulated or paper-execution environments. Simulated results have inherent limitations as they do not reflect the actual market impact, liquidity constraints, or slippage of real-money brokerage account routing. You are entirely responsible for your own risk and execution decisions.
Contact

Phone

888 668 6536

Email

info@raydar.online

© Copyright 2025 Raydar - All Rights Reserved

‌

AI Website Generator