1. Nature of the Program
The Raydar.online platform operates strictly as an independent Quantitative Research & Experimental Software Development Program. All data, tickers, and sequential signals generated within this environment are the direct real-time output of proprietary algorithmic data models.
2. Informational and Educational Purpose Only
This program does not provide financial, investment, legal, or tax advice. No signal, trigger, or message constitutes a solicitation, recommendation, or endorsement to buy or sell any financial instrument. The system is designed to showcase the velocity filters and processing capabilities of proprietary experimental software.
3. Execution Characteristics & Dynamic Risk Realities
Subscribers acknowledge that the data feed operates in a high-velocity market microstructure environment (specifically during the opening 30 minutes of the regular trading session).
• Selectivity: The data model is highly selective, filtering for extreme conditions. It may output zero signals on any given day, up to a structural maximum of 15 tickers per session.
• Flash Aborts / Immediate Cancels/ Sell: The algorithm is designed to protect mock capital pools by terminating or canceling trade ideas within seconds if immediate velocity parameters break down. Subscribers acknowledge that immediate sequential cancels or rapid exit signals are a core design characteristic of the experimental logic, intended to absorb negligible, minimal friction rather than chasing decaying momentum.
4. Simulation and Performance Realities
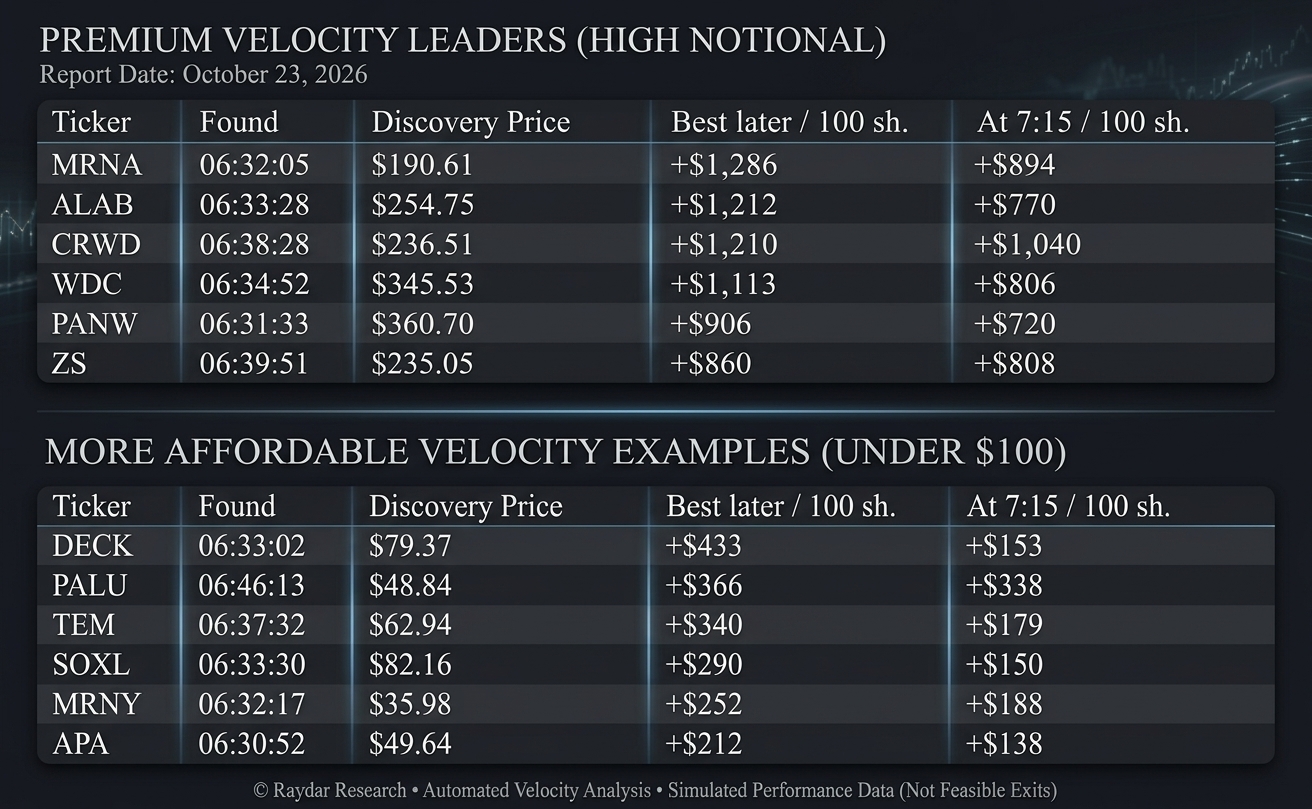
Any live streaming visuals (including YouTube broadcasts via OBS) or performance logs are based on real-time market data processed through simulated or paper-execution environments. Simulated results have inherent limitations as they do not reflect the actual market impact, liquidity constraints, or slippage of real-money brokerage account routing. You are entirely responsible for your own risk and execution decisions.